
Pensacola and the Florida Panhandle
Hurricane Isaias is headed for the Florida Panhandle. Protect your home and your insurance claim.
A few minutes before the storm can decide whether your claim is paid in full afterward. Here's how to prepare, what to do once Isaias passes, and who to call if your insurance company denies or underpays your hurricane damage claim.
What Hurricane Isaias could do to homes
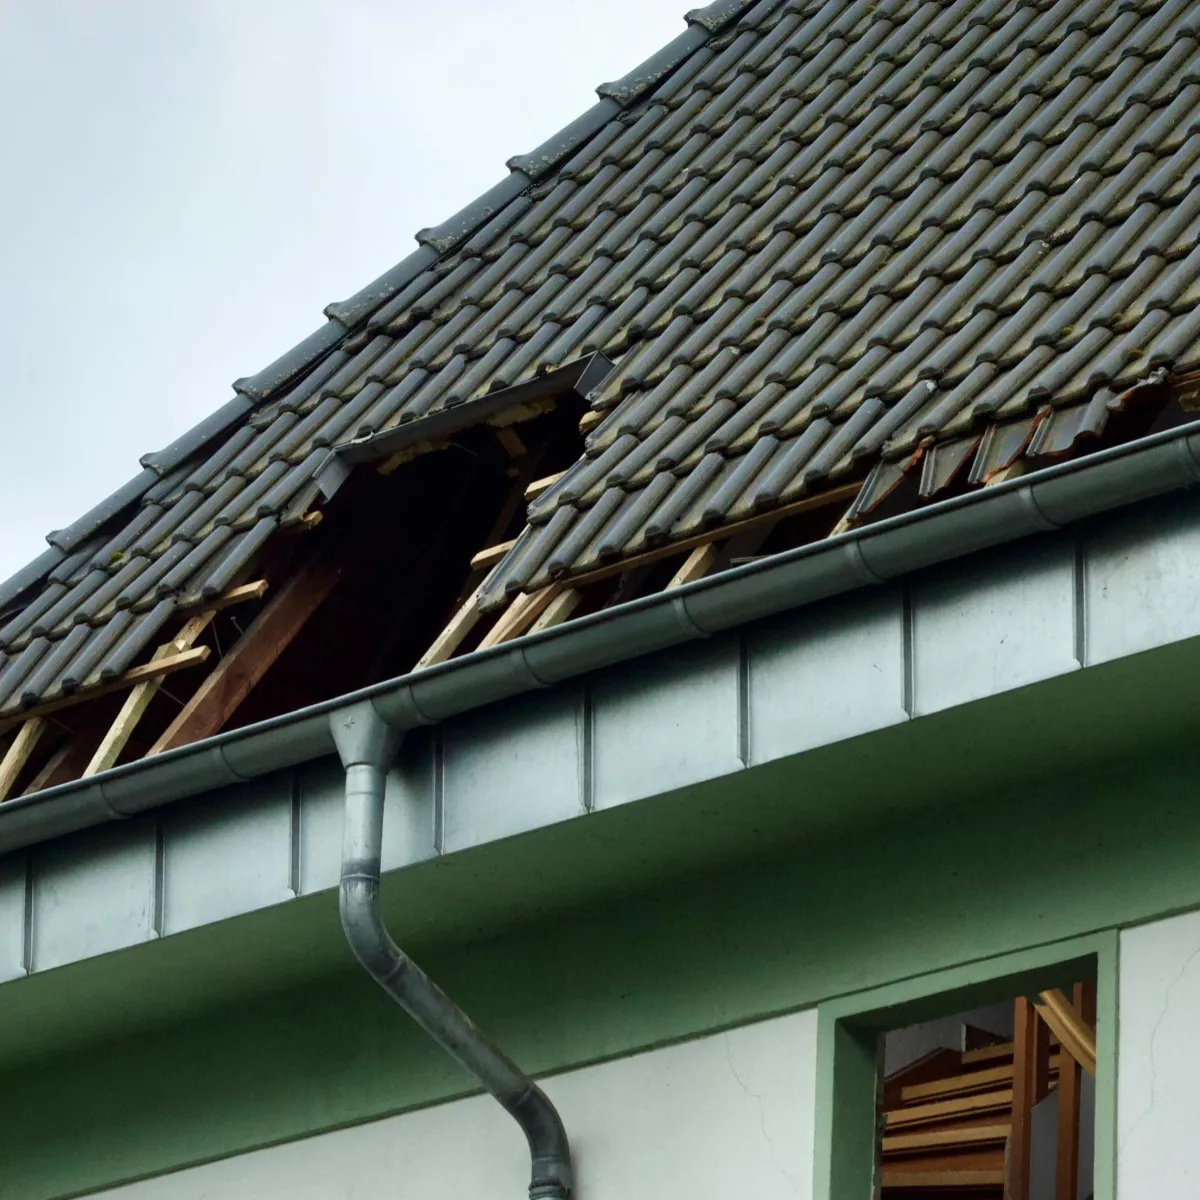
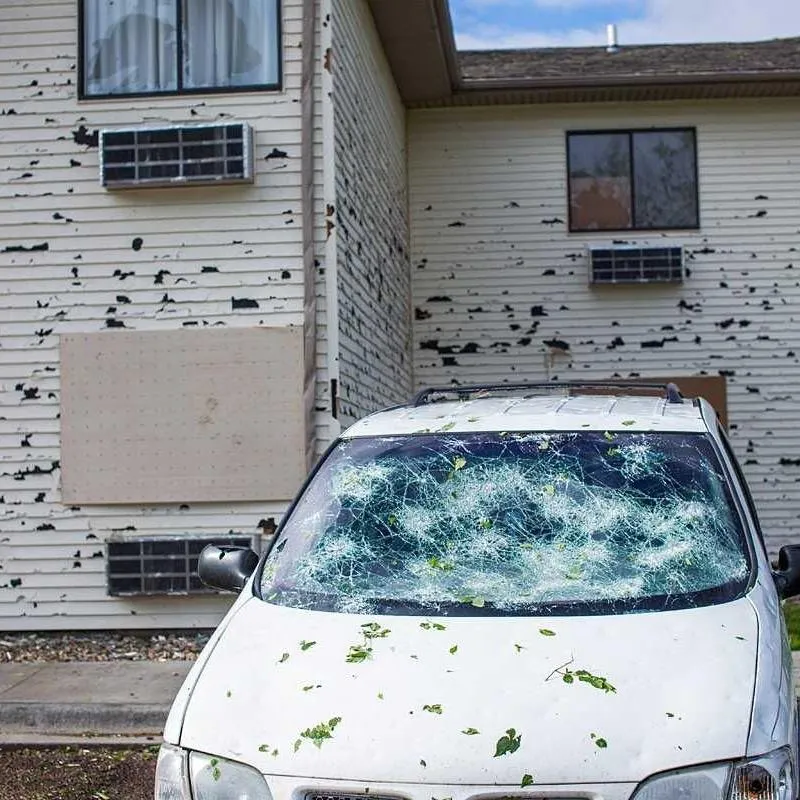
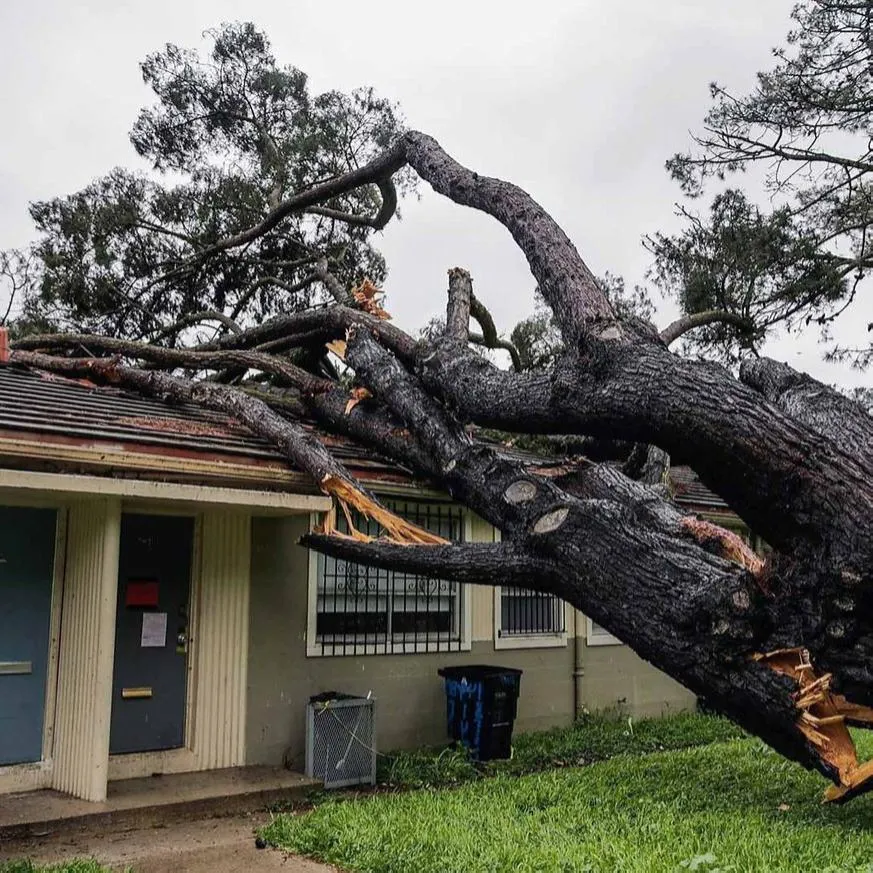
Forecasters expect Isaias, the first hurricane of the 2026 Atlantic season, to strengthen to a Category 2 or low-end Category 3 before landfall on the northern Gulf Coast. Each of these hazards leads to a different kind of property damage claim.
5–7 ft
Storm surge
Possible in vulnerable coastal zones. Surge damage is usually a flood insurance issue.
Up to 15 in
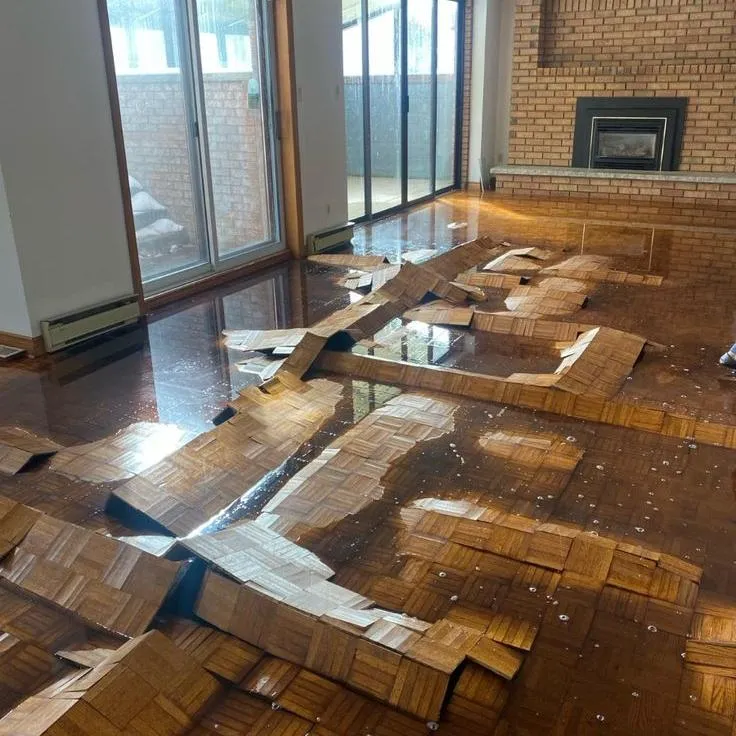
Heavy rainfall
Flash flooding and wind-driven rain that can enter through damaged roofs and windows.
High winds
Wind and tornadoes
Damaging winds and possible tornadoes from Alabama across the Panhandle into southwest Georgi
Days
Power outages
Long-duration outages expected near landfall, which can lead to spoiled contents and mold.
Before Isaias arrives: protect your future claim
After a hurricane, insurers often argue roof damage was “wear and tear” or “pre-existing.” Proof of how your home looked before the storm is one of the strongest answers. Only do what is safe, and leave if you're told to evacuate.
1. Photograph and video your home now. Walk every room, then the exterior and roofline, including from the street. Date-stamped footage of an intact roof is powerful evidence later.
2. Find your policy. Locate your declarations page and note your hurricane deductible, your insurer's claim phone number and your policy number.
3. Save copies off-site. Upload your photos, policy and receipts for major belongings to cloud storage or email them to yourself.
4. Check your flood coverage. Standard homeowners policies usually exclude flood and storm surge. Know whether you have a separate flood policy.
5. Secure your property and keep receipts. Shutters, plywood, sandbags and generator costs may matter to your claim.

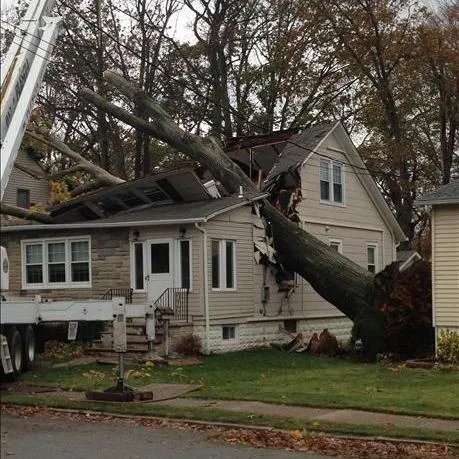
After Isaias passes: what to do first
Return only when officials say it is safe. Watch for downed power lines, gas leaks and standing water.
1. Document the damage before cleanup. Photograph the roof, ceilings, walls, floors and belongings. Keep damaged items if you can.
2. Stop further damage. Tarp the roof, dry out wet areas and keep every receipt.
3. Report your claim promptly. Write down your claim number, your adjuster's name and the date of every call.
4. Get a free policy review before you accept a denial or low offer. Call 813.999.2380.
A Florida property damage attorney on your side after Isaias
Karkatselos Law represents Florida homeowners and business owners whose property insurance claims are denied, delayed or underpaid. If Hurricane Isaias damages your roof or home in Pensacola or anywhere in the Panhandle, we'll review your policy for free and tell you plainly where you stand.
Questions about your Hurricane Isaias claim?
Call now, before or after the storm, for a free policy review.
How insurers deny and underpay hurricane claims
Florida homeowners hear the same reasons again and again after a storm. If you hear one of these after Hurricane Isaias, have your policy reviewed before you give up.
“Wear and tear” or “age of roof”
The insurer blames an older roof instead of Isaias winds for missing shingles and leaks.
“Below your deductible”
A low estimate leaves out interior damage so the total falls under your hurricane deductible.
“It was flood, not wind”
Wind damage is reclassified as excluded flood or surge damage.
“Pre-existing damage”
The insurer claims the damage was there before the storm.
“Faulty workmanship”
Storm damage is blamed on how the roof or windows were installed.
Delays and lowball offers
Slow responses and partial payments that don't cover the real cost of repairs.
Contact Karkatselos Law
Save our number before Isaias hits, and follow us for storm updates.
Contact Karkatselos Law
Save our number before Isaias hits, and follow us for storm updates.
Contact Karkatselos Law
Save our number before Isaias hits, and follow us for storm updates.
FAQ
Should I take photos before Hurricane Isaias hits?
Yes. Pictures of your home before the storm help prove the damage came from Isaias.
My insurer denied or underpaid my claim. Now what?
Don’t accept it yet. Call us for a free policy review.
Do you help homeowners in Pensacola?
Yes, across Pensacola and the Florida Panhandle. Call 813.999.2380.
Copyrights 2026 | Karkatselos Law Firm
Copyrights 2026 | Karkatselos Law Firm
Copyrights 2026 | Karkatselos Law Firm